Removing late payments from your credit report: What to know
Late payments can happen to anyone, and acting quickly to catch up could mean it never shows up on your credit report. But if you’re wondering how to remove a late payment that’s already on your credit report, the answer depends on whether the information is accurate.
If a late payment was accurately reported to the credit bureaus, there’s not much you can do to have it removed. But if you discover a late payment was reported in error, you can file a dispute to have it investigated and wiped from your credit reports.
What you’ll learn:
-
Accurate late payments can stay on your credit reports for up to seven years, but their impact on your credit scores generally lessens over time.
-
To get an incorrect late payment removed from your credit report, you need to file a dispute with the credit bureau that issued the report.
-
Creditors typically don’t report late payments made within 30 days of the due date to the credit bureaus, but they might still charge late fees or enforce other penalties.
-
Setting up automatic payments can help you avoid late payments, and regularly checking your credit can help you spot any errors.
How long do late payments stay on your credit report?
The Consumer Financial Protection Bureau (CFPB) says negative information, such as late payments, can stay on a credit report for up to seven years. This seven-year period generally begins from the date of the original delinquency, according to TransUnion®.
Late payments may affect your credit scores for that entire period, but their impact typically decreases over time. And if a late payment stays on your credit report for more than seven years, you may be able to dispute it and get it removed.
Can you get late payments removed from your credit reports?
If you made a payment on time but it was inaccurately reported as late, you can file a dispute and ask for the information to be removed. However, if a payment is accurately reported as late, you generally can’t have it removed from your credit reports.
The CFPB warns that you can’t pay a company to remove late payments either. If a company claims it can remove accurately reported derogatory marks from your credit reports, the CFPB has clear advice: “Don’t pay fees to ‘repair’ your credit history.”
Even if you miss a payment’s due date, paying your bill as soon as possible could have benefits. Here’s why: Creditors typically only report a late payment to the credit bureaus if it’s at least 30 days beyond the due date. So if you make the payment in full within that 30-day window, it may never show up on your credit reports at all.
Can you remove a 30-day late payment from your credit report?
A 30-day late payment that was accurately reported can’t be removed from your credit reports through the dispute process. But if the payment was reported incorrectly, you can dispute it.
How to remove late payments from your credit report
If you find an error on your credit reports—like a misreported late payment—here are a few steps to take.
1. Review your credit reports
Check your credit reports from all three major credit bureaus—Equifax®, Experian® and TransUnion—to see where the incorrect late payment appears. Some creditors report to all three bureaus, while others may only report to one or two.
You can request free copies of your credit reports by visiting AnnualCreditReport.com.
2. Compare the late payment with your records
It might be worth double-checking that the payment was inaccurately reported as late. Account statements, bank transactions and payment confirmations could be places to start.
If you’re able to verify you made the payment on time, gather any relevant documentation together to send with your dispute.
3. File a dispute with the credit bureau
According to the CFPB, the first step of the dispute process is to contact any credit bureaus that show the error on their reports. You can file a dispute online, by mail or by phone.
Here’s how to file a dispute online:
The CFPB also has additional contact information for each bureau and a template dispute letter.
4. Contact the creditor
The CFPB says the next step is to contact the creditor who reported the inaccurate late payment. Generally, once it receives your dispute, the creditor will investigate your claim and respond within 30 days.
5. Monitor the results
Once the investigation is complete, check your credit reports to make sure the inaccurate late payment was removed. The CFPB says that once its investigation is complete, the credit bureau should send you a written notice of the results and a copy of your updated credit report.
How do late payments impact a credit score?
Credit-scoring companies, like VantageScore® and FICO®, consider five factors when calculating your credit scores.
Among these, payment history is given the greatest weight. This is why even one late payment could hurt your credit scores. But it’s hard to know exactly how much late payments affect your scores. It depends on things like:
-
How late the payment is. The more time that goes by before a payment is made, the larger hit your credit could take.
-
How strong your credit was before the missed payment. If you have an excellent credit profile, one late payment could result in a bigger drop.
-
How many late payments there are. Multiple late payments can have a greater negative impact on your credit than a single late payment.
Removing late payments from credit reports FAQ
Long story short: You typically can’t remove legitimate late payments from your credit reports. But if you want to know more, here are the answers to some frequently asked questions about late payments and credit reports.
When are late payments reported?
Late payments typically aren’t reported to the three major credit bureaus until they’re at least 30 days past due. Late payments are typically also reported to the credit bureaus at 60, 90, 120 and 150 days past due. As those days add up, the impact of the late payment on your credit scores might grow.
Can you pay to have late payments removed from your credit report?
The CFPB says that you can’t pay a company to remove accurate negative information from your credit reports, including late payments. The agency warns against paying any company to “repair” or “fix” your credit.
Do late payments cause any other problems?
Late payments don’t just affect credit scores. They can also result in late fees and higher interest rates. If you have a new credit card with a promotional annual percentage rate, you could lose that too.
If a credit card account is 180 days past due, the issuer may close and charge off the account. This means the account is permanently closed, but the account holder still has to pay the debt. And some issuers might charge off accounts sooner than 180 days past due.
Can late payments on a credit report be removed before 7 years?
Late payments may stay on a credit report for up to seven years. They can only be removed earlier if they were reported in error and successfully disputed.
Key takeaways: How to remove late payments from your credit report
Accurately reported late payments can’t be removed from your credit reports. You can’t pay someone else to remove accurate information from your reports either. But if you find an error on your credit report, you can dispute it yourself. And even accurate late payments will fall off your credit reports after seven years.
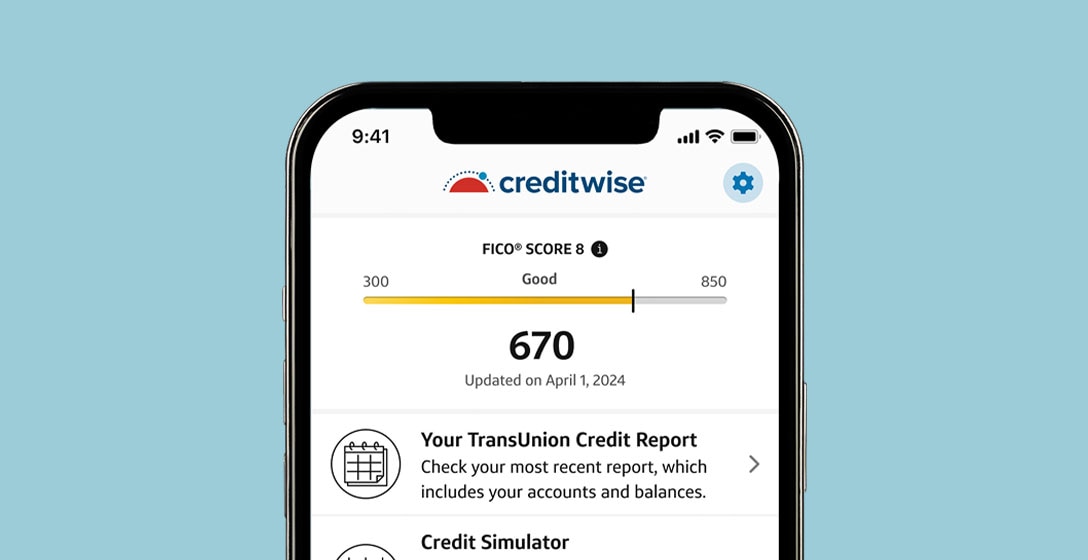
Regularly monitoring your credit may help you spot any errors on your credit reports. With CreditWise from Capital One, you can check your credit report and score anytime without affecting your credit scores. And CreditWise is free, even if you’re not a Capital One cardholder.