How often do your credit scores update?
It might seem like your credit score changes often, sometimes more than once a month. The frequency of these changes can depend on when lenders share information about your accounts with the three major credit bureaus. Credit-scoring companies may also calculate your credit score each time you or a creditor requests your score.
What you’ll learn:
-
Your credit scores may update when the three major credit bureaus—Equifax®, Experian® and TransUnion®—receive new account information from creditors.
-
Lenders typically update account information with bureaus every 30-45 days.
-
How much your scores change may depend on who reported the information and which credit-scoring model was used.
How often do credit scores update?
When and how often your credit scores update depends on when:
-
Your lender sends information to the three major credit bureaus
-
Credit bureaus make updates to your credit reports
-
Credit-scoring companies use those reports to update their scores
-
An authorized individual or organization requests your credit score
Lenders usually report updated information every 30-45 days. You might receive an updated credit score each month, but every lender has its own reporting schedule and policies.
Your scores may update more frequently—sometimes multiple times a month. This can vary, depending on how many lenders you have and when they send their updates.
What day of the month do credit scores update?
Generally speaking, there’s no set date each month when you can expect your credit scores to be updated.
What is rapid rescoring?
Rapid rescoring is a process lenders use to expedite updates to credit reports when considering a loan application. This allows lenders to get more up-to-date credit scores for the applicant instead of waiting the 30 to 60 days it typically takes for creditors to submit updates to credit bureaus. This is often used by mortgage lenders, who typically pay for the process and submit documentation on behalf of the borrower.
By taking steps like paying down credit card balances and having those changes reflected on credit reports, borrowers may improve their eligibility or get access to better loan terms.
How much can I expect my scores to vary?
It can be difficult to predict how—or by how much—your credit scores can change or vary. Credit-scoring companies like FICO® and VantageScore® use different formulas to calculate scores. And each credit-scoring company has several different versions of its credit-scoring models too.
Formulas can use information from just one credit report or a combination of different reports. Then, each formula may assign different levels of importance to that information.
How much your scores change depends on the information your lenders send to the credit bureaus. Examples of information they share may include:
-
When you applied for a new account
-
When you opened or closed an account
-
Your account balance
-
Your credit limit or the amount of a loan
-
The timeliness of your payments
-
When an account goes into collections
This information directly relates to factors that affect your credit scores, including your credit history, payment history, credit utilization ratio and credit mix.
Where can I find my most up-to-date credit scores?
There are a few places you can go to check your credit scores, including:
-
Credit card issuers
-
Credit bureaus
-
Credit-scoring companies
-
Credit counselors
-
Online tools
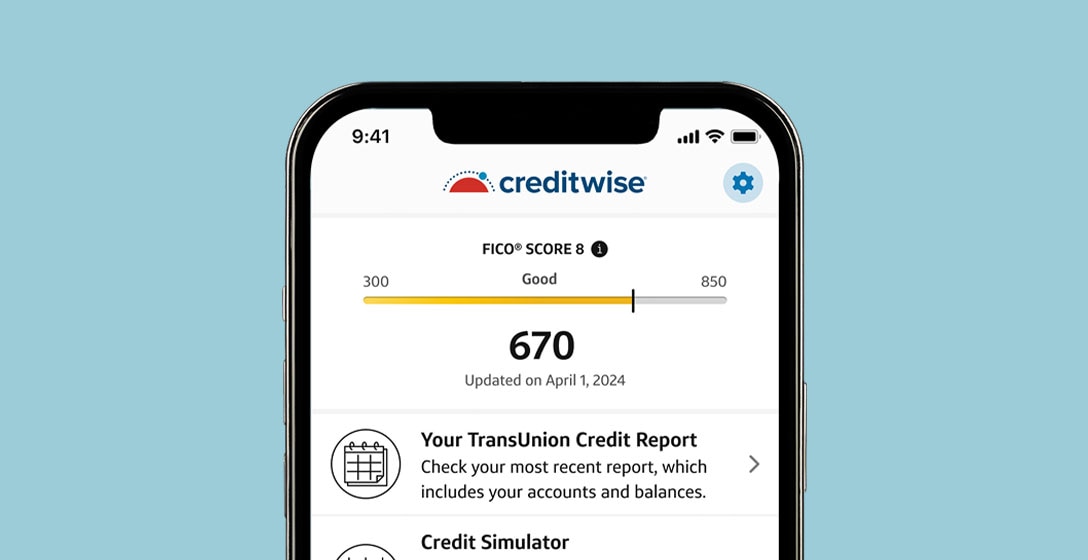
CreditWise from Capital One lets you monitor your credit report and score anytime, without hurting your credit scores. And you can use the CreditWise Simulator to learn how your scores might go up or down if you do things like open a new credit card, pay off a balance or increase your credit limit. CreditWise is free, even if you aren’t a Capital One cardholder.
You can also get free copies of your credit reports from all three major credit bureaus at AnnualCreditReport.com.
How to increase your credit scores
Building your credit scores can take some time. But here are some strategies for improving your credit that can help you move in the right direction.
-
Pay bills and debts on time. On-time bill and debt repayment is important to building a strong payment history, which accounts for 35% of your FICO score.
-
Pay down revolving debt like credit cards. Revolving credit balances make up 30% of your FICO score. By paying down revolving debts, you can help lower your credit utilization ratio—a significant factor that influences your credit scores.
-
Keep your oldest credit card account open. The length of your credit history accounts for 15% of your FICO score. Closing an older card could hurt your credit scores by reducing your overall credit age.
-
Only apply for the credit you need. Financial institutions typically do hard credit checks when you apply for credit, which can temporarily lower your score. Credit checks and the age of your newest account can make up 10% of your FICO score.
-
Diversify your credit mix. This refers to the variety of credit types you have, like auto loans, mortgage loans and credit cards. Credit mix makes up 10% of your FICO score. And a diverse credit mix can help your credit scores.
-
Correct any errors in your credit reports. Be sure the information in your credit reports is accurate. Common errors include accounts belonging to other people, incorrect account balances, inaccurate late payment reports and debts being listed more than once. You can dispute errors on your credit reports by contacting the three major credit bureaus.
Credit score updates FAQ
Here are the answers to some frequently asked questions about updates to credit scores.
Why did my credit scores decrease after paying off debt?
It might seem counterintuitive that paying off debt could hurt your credit scores, but it can happen. For example, paying off an installment loan could decrease the diversity of your credit mix and/or the average age of your credit accounts, which can lower your credit scores.
What’s the highest your credit scores can jump in one month?
There isn’t a specific threshold for how high your credit scores could increase in a given month. The exact increase can vary based on the particular individual’s credit profile and the credit-scoring model used.
Do all three credit bureaus update at the same time?
No, credit bureaus typically don’t update credit information at the same time. They rely on reports from lenders to make updates—and lenders’ schedules often vary since they choose their own reporting dates.
Why hasn’t my credit score updated yet?
If your credit score hasn’t been updated, the credit-scoring companies may not have received or processed new information about your credit file yet. The major credit bureaus typically provide credit-scoring agencies with a monthly update about your credit situation. It can take some time for:
- Credit bureaus to process information from lenders and update your credit file
- Credit-scoring companies to receive and analyze information from credit bureaus
Key takeaways: How often does your credit score change?
Your credit scores change based on the information in your credit reports, among other factors. You can’t control how often they update. Whether you’re trying to maintain or improve your credit scores, it’s important to monitor your credit regularly. And CreditWise is one way to do that without hurting your credit scores. You can also get free copies of your credit reports by visiting AnnualCreditReport.com.
Over time, credit monitoring might give you a deeper understanding of the factors influencing your scores. You’ll have a better idea of where you stand financially. And you can use that credit information to take the next steps toward your financial goals.