Why did my credit card APR increase?
Your credit card’s annual percentage rate (APR) might increase for a variety of reasons. Sometimes it can’t be prevented, like when it changes alongside the prime rate. But in other instances, your APR depends on you and how you use your credit card.
What you’ll learn:
-
A credit card’s APR could increase due to a rise in the prime rate or a drop in your credit scores.
-
You may be able to avoid some APR increases with responsible credit card use and good financial habits.
-
If your credit card APR rises, you can work on paying down your balance to avoid costly interest charges.
5 possible reasons why your APR increased
Credit cards typically have multiple APRs associated with them. And there are many factors that might affect your APRs. If your issuer is like Capital One, you can find out more about rates and how they’re determined by reading your monthly statement.
But for now, here are a few reasons your APR could have increased:
1. The prime rate changed
There are two basic types of APR: variable and fixed rate. Most credit cards have a variable APR. As the name suggests, a variable APR will likely change throughout the course of the loan. That’s because it’s tied to an index interest rate like the prime rate. When the prime rate changes, so does the credit card APR.
2. The promotional period ended
If you opened a new credit card with a lower limited-time introductory APR or accepted a lower promotional rate on an existing card, the promotional period may have ended. If that’s the case, you may be seeing the card’s standard rate, and that could be applied to the remaining balance.
The Consumer Financial Protection Bureau (CFPB) says an introductory APR period must last at least six months unless you become more than 60 days late on your payment.
3. You took out cash advances
A cash advance is a type of transaction you can make with your card that comes with a higher APR than regular credit card purchases. Cash advances also might not have a grace period, meaning any interest is applied right away. So if you’ve used your card to take out a cash advance, a higher APR and fees will apply to that transaction but should remain the same for regular transactions.
You can check with your credit card issuer about which types of transactions are considered a cash advance.
4. You violated the terms of your credit card agreement
If you violate the terms of your card agreement, you may incur a penalty APR, where the APR on your card increases for a period of time. If you do this with a card that has an introductory APR, the issuer may void that rate altogether.
Penalty APRs could apply to things like violations of your credit limit and repayment terms. Federal law requires credit card issuers to provide 45 days’ notice before imposing the increase. And that notice will list the penalty APR and explain the reason for the change.
5. You weren’t using your card responsibly
If you haven’t been using your credit card responsibly, your credit scores may drop. And according to the FDIC, if your credit scores drop significantly, your credit card issuer might decide to raise your APR. Responsible card use includes doing things like making monthly payments on time and using only the credit you need.
Options if your credit card APR increased
If your APR has gone up and you’re worried about managing payments and interest, you could consider credit card consolidation. A balance transfer, for example, could lower your APR and reduce your minimum monthly payments. You may also find that streamlining multiple monthly payments into a single payment helps you stay more organized.
Keep in mind that transferring a balance doesn’t eliminate the credit card debt. And regular interest rates generally apply to balance transfers and new purchases after the introductory period ends.
Key takeaways: Why credit card APR increases
There are a few reasons why your credit card APR can increase, including fluctuations in the prime rate, an introductory period ending and changes to your credit scores. You can prevent some of these by doing things like using your credit card responsibly.
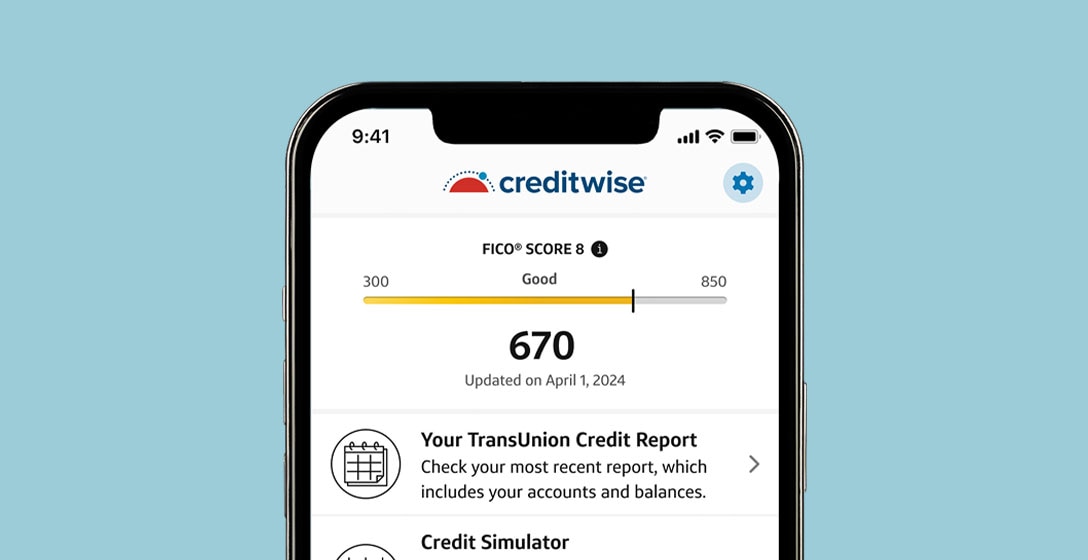
Your credit scores influence the interest rate you qualify for. Regularly monitoring your credit can help you understand how your financial activity impacts your scores. CreditWise from Capital One gives you free access to your credit report and credit score. You don’t have to be a Capital One customer, and using it won’t hurt your credit scores. You can also get free copies of your credit reports by visiting AnnualCreditReport.com.