Credit basics & cards with no preset spending limit (NPSL)
Explore credit-scoring factors, including credit utilization, and how they apply to NPSL cards.

If you have a card with no preset spending limit (NPSL), you already know it functions much like a traditional credit card—with the benefit of tailored purchasing power.
That flexibility is possible, in part, because NPSL cards don’t have fixed credit limits. The lack of defined limits also changes how issuers like Capital One report NPSL accounts to credit bureaus. But as you’ll read, NPSL cards are still relevant to credit scoring.
What you’ll learn:
-
FICO® says basic credit scoring factors are amounts owed, payment history, length of credit history, credit mix and new credit.
-
NPSL cards don’t typically affect credit utilization ratios, one aspect of amounts owed.
-
NPSL cardholders can maintain their credit scores by using their cards responsibly and following payment terms.
-
Capital One offers select customers cards with no preset spending limit.
Where do credit reports and credit scores come from?
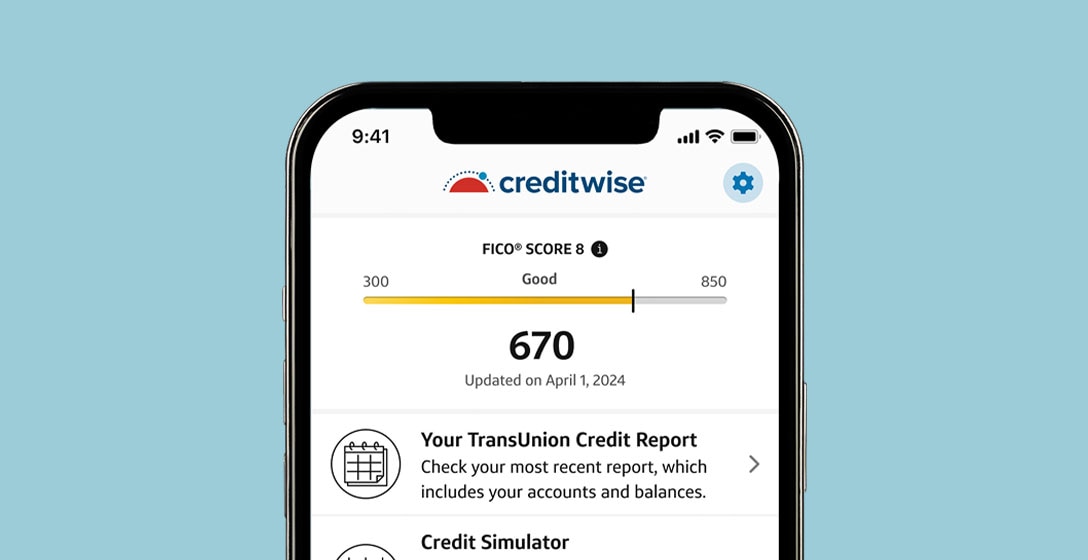
The basics of credit reporting and scoring apply whether you have an NPSL card or a traditional credit card:
-
Credit bureaus produce credit reports using information from lenders and others.
-
Credit-scoring companies use those credit reports to calculate credit scores.
-
Credit card issuers, banks and other businesses use credit scores to help determine creditworthiness, make lending decisions and more.
How do NPSL cards affect credit reports and scores?
Credit reports and scores offer a summary of credit activity and history. You can get an idea of how NPSL cards fit in by examining FICO credit-scoring factors.
Most factors apply to NPSL cards the same way they do to traditional cards. But let’s start where things are a little different.
1. Amounts owed, including credit utilization ratio (30%)
There are multiple aspects to amounts owed. One part, credit utilization, is notable because it doesn’t typically apply to NPSL accounts.
Why? Credit utilization compares how much revolving credit someone is using to how much they have available. NPSL cards don’t have fixed credit limits, so there’s no basis for comparison, and there may be nothing for card issuers to report.
That’s the case at Capital One. And it means if you have a Capital One NPSL card, it won’t be considered as part of your credit utilization ratio.
You might consider that a good thing. High utilization ratios can negatively impact credit scores. But with an NPSL card, your scores might not be penalized in the same way for major purchases or high monthly spending. Plus, FICO and other experts say the most important thing for credit scores is paying statements on time.
2. Payment history (35%)
In general, a good payment history for NPSL cards involves paying off statements on time every month or following payment terms if you carry a balance. It’s the same principle that applies to traditional credit cards.
3. Length of credit history (15%)
FICO defines length of credit history in a few ways, including “the age of your oldest account, the age of your newest account, and an average age of all your accounts.” Generally, scoring models consider NPSL cards, traditional cards and other loans when assessing credit age.
4. Credit mix (10%)
Having different types of credit and loans (NPSL cards, traditional credit cards, mortgages or auto loans) can signal to lenders that you can manage a variety of accounts. Adding an NPSL card could diversify your credit mix.
5. New credit (10%)
Applying for a new NPSL card can result in a hard inquiry. As with most credit card applications, a hard inquiry related to an NPSL card can cause a temporary dip in your credit scores.
Key takeaways: NPSL cards and credit basics
Capital One doesn’t report a limit for cards with no preset spending limit. That means NPSL cards won’t factor into credit utilization ratios the same way as traditional credit cards. But other credit scoring factors—including payment history, credit age and credit mix—are similar to fixed-limit cards.
Capital One offers a variety of credit cards to fit your lifestyle. Compare cards and find one that’s right for you.