How to prevent accounts payable fraud
Summary
-
Accounts payable fraud typically involves schemes that manipulate your business’s accounts payable processes to illegally access funds.
-
Common types of accounts payable fraud include invoice fraud, check fraud, wire transfer and ACH fraud, ghost vendor schemes, employee reimbursement fraud and kickback schemes.
-
Accounts payable fraud red flags can include invoice inconsistencies, errors in vendor information, unusual payment activity and changes in employee behavior.
-
You can implement accounts payable fraud prevention controls like dividing financial duties among employees and tightening invoice approval and payment workflows.
Preventing accounts payable fraud starts by understanding how these schemes work and implementing practical safeguards that reduce your business’s risk. Taking these steps can help protect your business, keep your finances secure, maintain strong vendor relationships and avoid damage to your reputation.
Learn how to recognize common fraud schemes and use prevention controls that can help you better identify potential risks and strengthen your accounts payable processes.
What is accounts payable fraud?
Accounts payable fraud occurs when someone intentionally takes advantage of your company’s accounts payable processes to obtain unauthorized payments or steal money or assets. Because your accounts payable department manages invoices and payments, it can be an easy target for fraudsters.
Accounts payable fraud may involve an employee, a vendor or even an outside cybercriminal exploiting weaknesses in invoice approval, payment processing or vendor information. It can occur at various points throughout the payment cycle, from initial vendor setup to payment submission.
How does fraud in accounts payable work?
Fraud in accounts payable typically involves fraudulent invoices, unauthorized payments or other deceptive schemes that result in financial losses. It can be internal—committed by an employee—or external, like a criminal posing as a vendor.
For example, you might receive an invoice from a vendor that looks legitimate, so it goes through the approval process without proper verification. But later it’s discovered that the invoice was fake or the payment information was changed and money was sent to a fraudster.
What are the most common types of accounts payable fraud schemes?
Common types of accounts payable fraud include invoice and billing fraud, check fraud, ghost vendor schemes, wire transfer and ACH fraud, employee reimbursement fraud and kickback schemes. Here’s a closer look at each of these six types.
1. Invoice and billing fraud
Invoice fraud can involve duplicate invoices, where the same invoice is submitted more than once, resulting in multiple payments. Sometimes these duplications are the result of employee errors, but in other cases they stem from dishonest vendors or fraudulent activity.
Invoice fraud may also occur when a vendor, or someone impersonating a vendor, submits fake invoices for goods never delivered, services never performed or purchases not authorized. It can also involve invoices with inflated prices.
2. Check fraud
Check fraud typically occurs when an individual steals company checks, forges signatures or alters payee or payment information before the checks are deposited into an account controlled by a fraudster.
3. Ghost vendor schemes
A ghost vendor is a type of billing scheme. Someone—typically an employee—sets up a fake business in the company’s accounting system with the intent to generate and approve invoices that direct payment to themselves. For example, an employee might set up a vendor called “ABC Supplies,” then submit invoices for supplies that were never delivered and approve payment for them.
4. Wire transfer and ACH fraud
Cybercriminals use phishing emails, business email compromise (BEC) attacks and compromised accounts to convince employees to wire funds or update ACH payment information, like bank account or routing information. The fraudster might impersonate a company executive or a trusted vendor, making the request look legitimate.
5. Employee reimbursement fraud
This type of accounts payable fraud involves employees submitting fake or duplicate receipts, inflating expense reports or disguising personal purchases as business expenses.
6. Kickback schemes
Kickback schemes are another type of internal employee fraud. In this case, an employee might accept money, gifts or other benefits from a vendor in exchange for awarding contracts, approving inflated invoices or overlooking poor-quality goods or services.
Warning signs of accounts payable fraud
Warning signs of accounts payable fraud can include issues with invoices, vendor information, payment activity and employee behavior. Recognizing these red flags can help you identify potential fraud earlier and protect your business’s assets.
- Inconsistent invoices: Issues with invoices that could indicate accounts payable fraud include unusually high amounts, duplicate invoice numbers, invoice totals that are consistently rounded numbers or amounts that fall just under the maximum approval level.
- Errors in vendor information: Red flags for accounts payable fraud with vendors might include sudden changes in vendor details, such as updated contact or banking information, or vendor mailing addresses or bank account information that match an employee’s.
- Unusual payment activity: You might notice unusual activity, like an unexpected increase in invoices or a rush in the approval process. Repeated payments to the same vendor or payments that fall outside the normal cycle might also be signs of accounts payable fraud.
- Changes in employee behavior: Employees who insist on handling invoices and payments on their own, refuse to share information or responsibilities, or develop undisclosed relationships with vendors might also be red flags for accounts payable fraud.
Accounts payable fraud prevention controls
You can help prevent accounts payable fraud in your business by taking a few steps, like separating financial duties, verifying new vendors, tightening your approval and payment processes, and providing regular employee training. Using accounts payable automation may also help reduce the risk of accounts payable fraud.
Separate financial responsibilities
One person in your organization shouldn’t control the entire accounts payable process. Separate responsibilities like vendor setup, invoice approval, payment processing and account reconciliation among different employees. Whenever possible, the same person shouldn’t be in charge of both bookkeeping and check signing.
Verify new vendors
As your business grows and starts working with additional vendors, verify that each new vendor is legitimate before adding it to your system. Confirm its address, tax identification number (TIN) when applicable, banking information and contact details. You may also want to confirm the vendor’s payment instructions directly using a trusted phone number before issuing the first payment.
Strengthen approval and payment processes
Implement standardized policies and workflows for invoice approval and payments. You can use a process that matches purchase orders, receipts and invoices before approving payment. And for larger payments, consider requiring approval from two authorized employees.
Educate and train employees
Provide consistent training to employees to help them recognize accounts payable fraud red flags early. Your team should know how to watch for phishing emails, fake invoices and vendor schemes—and how to report any suspicious activity.
Consider accounts payable automation
Accounts payable automation software can help strengthen accounts payable fraud detection and prevention by reducing some of the manual work that can lead to human error and by increasing visibility into suspicious transactions. Automation software typically includes fraud detection and security features that can help identify red flags like duplicate invoices and unusual payment activity.
How Accounts Payable from Capital One Business can help reduce fraud
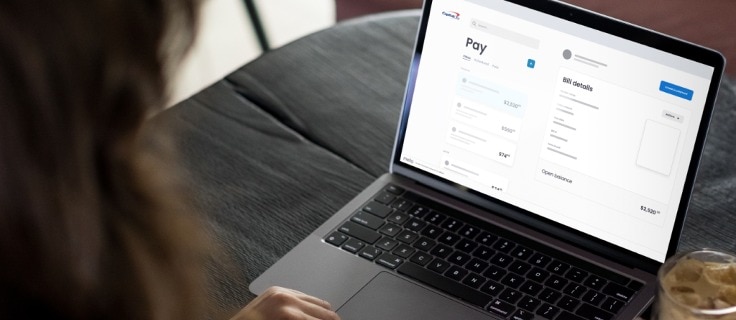
Accounts Payable from Capital One Business offers enhanced security features that can help reduce the risk of accounts payable fraud. When you pay vendors directly through your Capital One Business account, you can better protect your business and reduce its exposure to check fraud.
It also includes built-in fraud protections with every payment: Your bank account information stays private when you pay by ACH or check, and card payments offer an additional layer of security.
Key takeaways
While no business can eliminate the risk of accounts payable fraud completely, putting the right controls in place can make it much harder for fraudsters to succeed. Simple steps like separating financial responsibilities, verifying vendors, strengthening approval and payment workflows, and using accounts payable automation can go a long way toward protecting your business.
If you’re looking for additional security features and a more streamlined way to manage vendor payments, Accounts Payable from Capital One Business can help simplify your payment process while adding built-in protections against common types of payment fraud.