What is a credit card hold & how does it work?
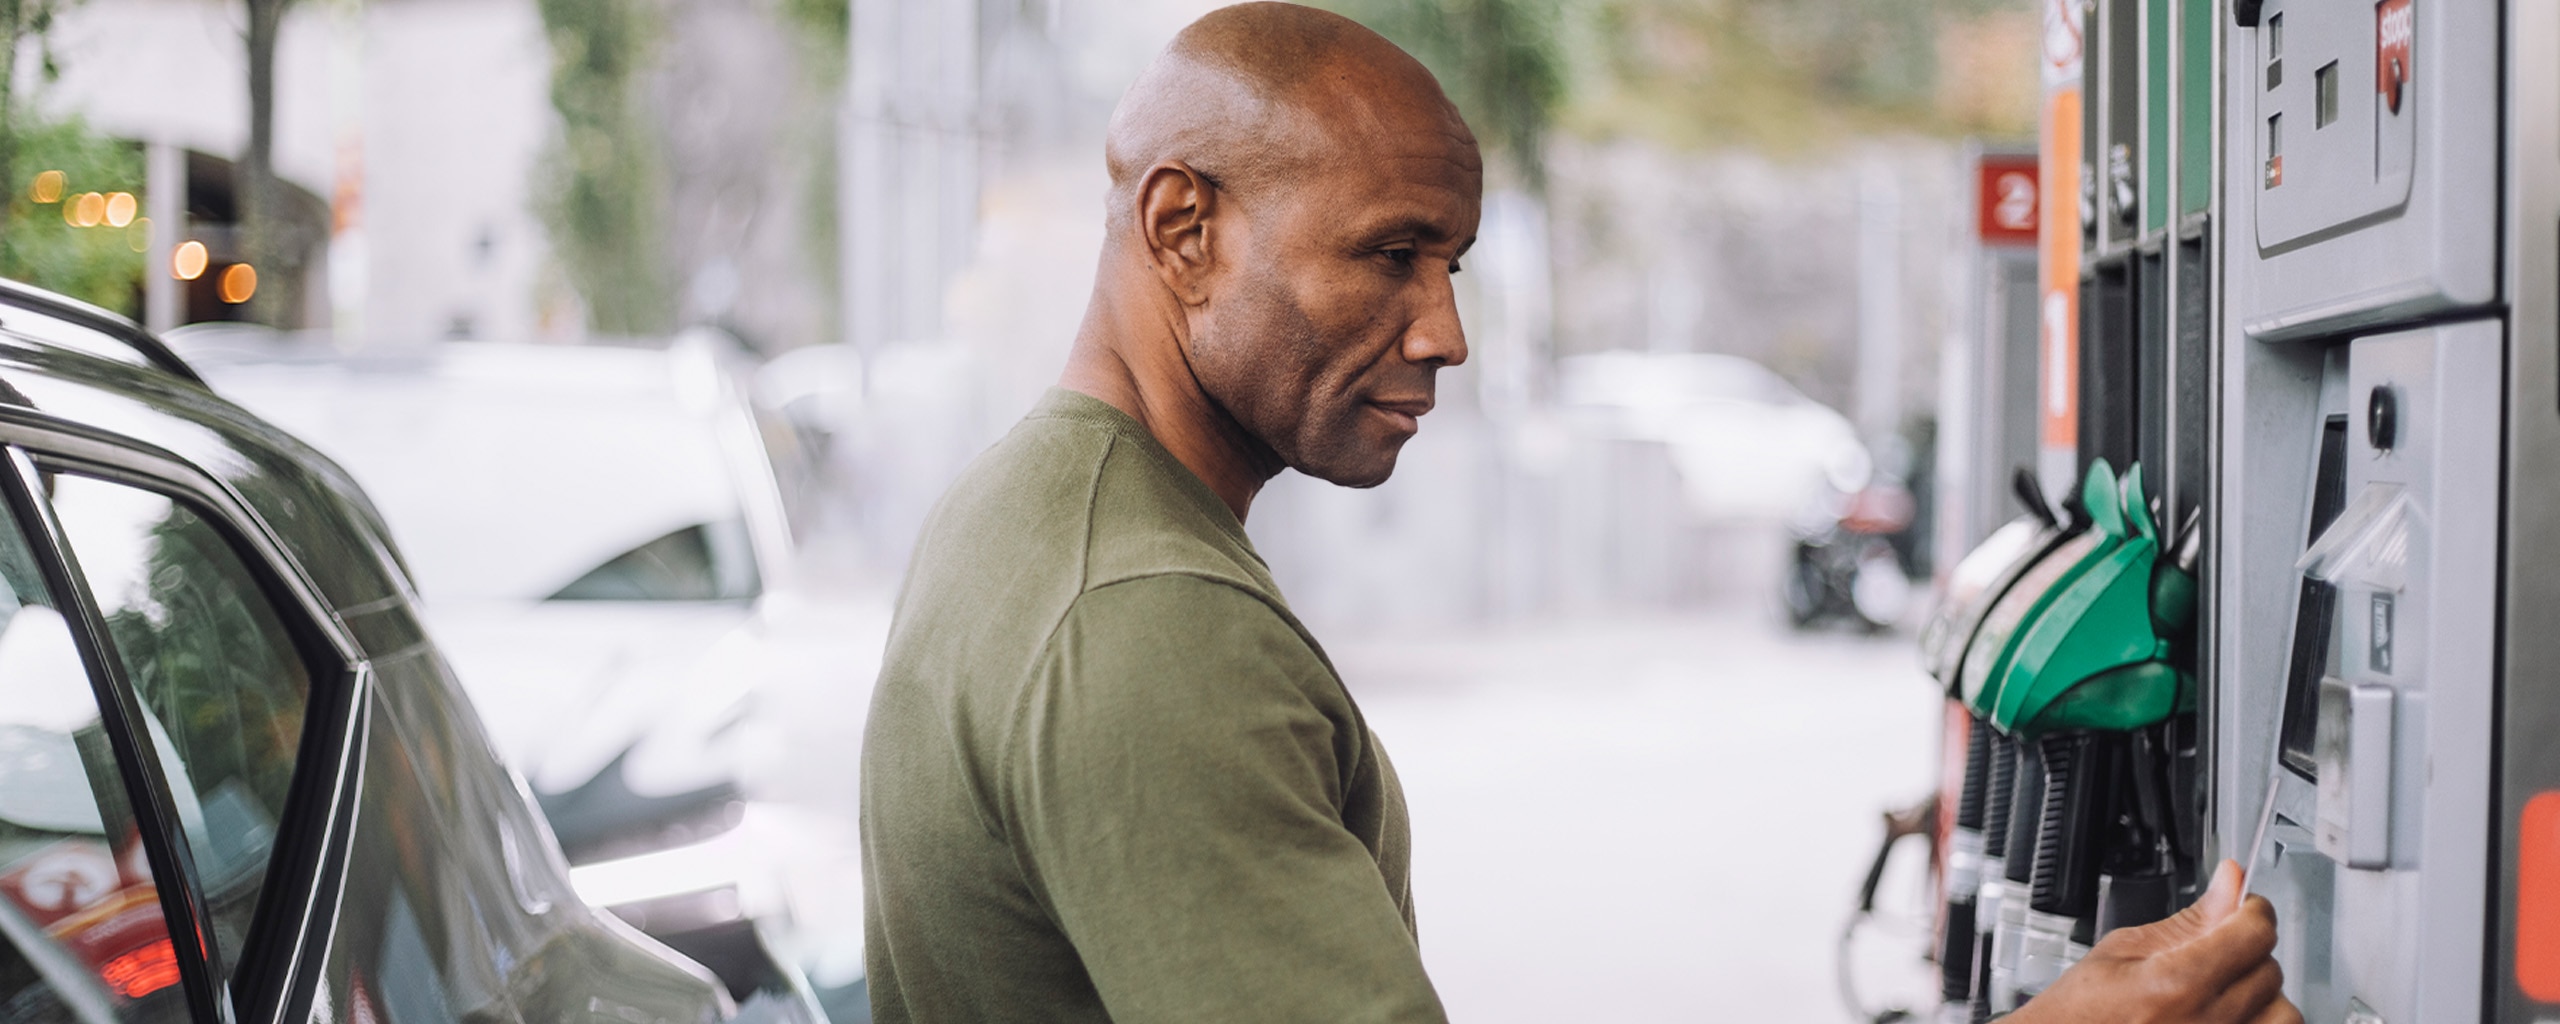
Have you ever used a credit card to check into a hotel only to notice a pending charge on your account during your stay? Or maybe you’ve seen one after paying for gas at the pump. That’s known as a credit card hold. There’s also a different kind of credit card hold that card issuers use when cardholders make late payments or go over their credit limit.
Learn more about how card holds work, how the two types of credit card holds differ, and how to remove and avoid credit card holds.
What you’ll learn:
-
There are two main types of credit card holds: authorization holds and administrative holds.
-
Authorization holds temporarily reduce your available credit while a transaction is finalized.
-
Administrative credit card holds are placed by card issuers if cardholders exceed their credit limit or make late payments.
-
Credit card holds may last anywhere from a few minutes to a month, depending on the transaction or type of hold.
What is a credit card hold?
A credit card hold is a temporary freeze on a portion or all of a credit card’s credit limit, set by a company or the lender. Until it’s removed, the hold reduces the amount of credit you can use. A hold isn’t the same as a regular purchase. And the hold amount may never be processed as a purchase. It simply blocks or “holds” a certain amount of the card’s credit limit for a period of time.
Businesses and organizations that commonly use credit card holds include:
- Hotels
- Gas stations
- Rental car companies
- Restaurants
- Credit card issuers
Types of credit card holds
There are two main types of credit card holds: authorization holds and administrative holds. Here’s how they work.
Authorization hold
Authorization holds—also called pre-authorizations—happen when a merchant temporarily places a hold on a credit card for a certain amount to verify that the card works and has enough available credit to cover a transaction. Businesses like hotels and rental car companies commonly use credit card holds.
For example, when you pick up your rental car, you might not pay the bill right away. Instead, the rental car company may put a hold on your credit card until you return the car and pay the final bill. Authorization holds can also function as a security deposit. So if the rental car comes back damaged, the hold amount may be processed as a transaction to cover it. And if you return the car without damage, you’ll pay the final bill amount and the hold will be removed from your card.
If you check your credit card account online, you may see an authorization hold appear as a pending transaction. The hold reduces your available credit, but it won’t become a posted purchase until the final transaction has been processed.
Administrative hold
Some card issuers may place an administrative hold if you exceed your credit limit or make late payments. The hold will typically stay on the card until the current balance is paid down to below the card’s credit limit or you consistently make on-time payments.
Late payments and going over a card’s credit limit can also show up on your credit report and affect your credit scores.
How long does a hold last on a credit card?
A credit card hold typically lasts anywhere from a few minutes to a month. It generally depends on the type of hold—whether it’s an authorization or an administrative hold—and the type of business that placed the hold.
For example, the length of an authorization hold depends on the type of transaction, when the merchant finalizes the purchase and whether you use the same card to pay the final bill.
Some credit card holds may clear soon after you pay the bill, while others may take a few days. And according to the Federal Trade Commission (FTC), if you use a different payment method—one that doesn’t have the hold on it—to pay the bill, the hold may stay on your card for up to 15 days.
How to remove a hold on a credit card
What you can do to remove a credit card hold typically depends on the type of hold:
-
Removing authorization holds: Authorization holds are typically removed when the merchant finalizes the transaction. When you check out of a hotel or return a rental car, you can ask if the company can immediately remove the authorization hold after you pay the final bill or for an estimated time when the hold will be removed. If the hold doesn’t clear as expected, you’ll need to resolve the issue with the merchant.
-
Removing administrative holds: To remove an administrative hold from your credit card, work on making consistent on-time payments and paying down your balance so it’s below your credit limit.
Tips to avoid a credit card hold
You generally can’t completely avoid authorization holds. But here are a few tips from the FTC to help avoid problems related to credit card authorization holds:
-
Check with the merchant. When you make a purchase or reservation, consider asking the merchant if they plan to place a hold on your card, especially if you’re giving your card information ahead of time.
-
Use the same payment method. When possible, use the same card for hotel or rental car reservations to pay the final bill. Using a different method could potentially cause the hold to stay on your account longer.
-
Talk to your card issuer. If you have questions the merchant can’t answer, you can contact your card issuer for more information about card holds. The card issuer may be able to tell you whether they allow card holds, how long they typically last and if there are any restrictions on what kinds of merchants can place card holds.
Credit card hold FAQ
Still have questions about credit card holds? Check out the answers to these frequently asked questions:
Can I still use my credit card if it’s on hold?
Whether you can still use your credit card when it’s on hold depends on the type of hold. If it’s an authorization hold, you can use the card as long as you have available credit left over.
But if your card issuer places an administrative hold on your account, you won’t be able to use your card for new purchases until the hold is removed. Depending on the card issuer’s policies, you may need to pay down your balance or make consistent on-time payments before you can use the card again.
Is a credit card hold a charge?
No, a credit card hold isn’t a charge. It’s a temporary hold or block on a certain amount of your credit limit. In some cases, the hold may be larger than the final transaction amount. But you’ll only see the final transaction amount on your statement after the hold is removed.
But keep in mind that all or part of a credit card hold may be processed as a transaction to cover damage.
What can go wrong with a credit card hold?
One thing that could go wrong with a credit card hold is that it could restrict your ability to make new purchases if it limits your available credit. In some cases, a hold may remain on your account as a pending transaction even after the bill is settled. If that’s the case, consider contacting the merchant to get the hold removed.
What are debit card holds?
Holds can also be placed on debit cards. With debit card holds, a portion of the card’s account balance will be temporarily unavailable.
If a debit card hold causes your account balance to dip too low, it could cause checks to bounce or other payments to be declined. So make sure to keep a close eye on your checking account balance before making any payments.
Key takeaways: Credit card holds
Seeing a hold on your credit or debit card can be startling if you don’t know why it’s there. But credit card authorization holds are common and often only temporary. They’ll typically be cleared once the final transaction goes through or at the end of a reservation once it’s determined that no damage needs to be covered. But if you’re worried about a hold when you book your next hotel stay or reserve a rental car, consider asking about their credit card hold policy so you’ll know what to expect.
If you’re looking for ways to get the most out of your travel expenses—and earn rewards or miles—you might consider a Capital One rewards card. Get started today by comparing the different Capital One credit cards to find one that best meets your needs. You can also see if you’ll be approved first—with no impact on your credit scores.