Auto Financing: 5 Essentials You Need When Applying for a Car Loan
Gather these key documents, and you’ll be ready to roll when it comes time to sign.

Updated March 06, 2026
Capital One
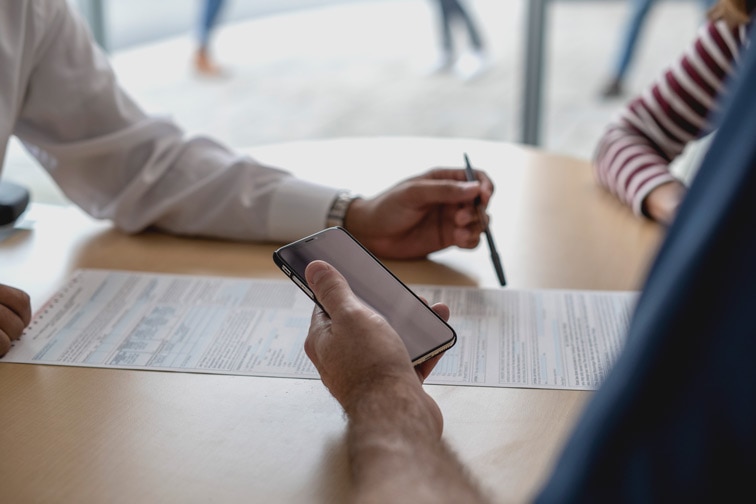
Before sitting down to sign any car loan paperwork, have these documents in hand to efficiently move through the process. Learn more about what to expect when you start the auto financing process.
The Essentials to Bring When Applying for a Loan
These are the documents you should have on hand when applying for a car loan. Always check with the lender before you come in to ensure that you have everything in order.
- Driver’s license: Bring a valid government ID, like a driver's license, to verify your identity.
- Proof of income: To verify your income, bring a recent pay stub. Check with the lender to see what information it needs to include. If you're self-employed, bring your past three months of personal bank statements.
- Proof of residence: Some lenders will use your driver's license as proof of residence, but you may need to provide a recent mortgage statement or utility bill.
- Proof of insurance: Contact your insurance company, and let them know you’re buying a new vehicle. Some policies extend temporary coverage (7 to 30 days) for new cars, and you’ll simply show your current insurance card to the dealer. However, it’s best to talk to your insurance provider before heading to the dealership, and find out if (and how much) your premiums will change for the new vehicle. Often, you can obtain a VIN, or vehicle identification number, of a vehicle you like just by checking a dealership’s website. With that in hand, you can obtain a quote from the insurer.
- Title and registration: If you’re trading in a vehicle, bring its title and registration information to verify ownership.
What Should You Know About Auto Financing?
Buying a car is one of the biggest financial transactions that you may make, outside of purchasing a home. Unless you pay out of pocket using cash, you'll need to take out a car loan to complete the transaction. After establishing your down payment, the upfront payment you will make toward the cost of the vehicle, you will be left taking out a loan for the principal, or the money you agree to pay back.
The most common types of car loans are simple-interest loans. In simple interest loans, interest will be charged only on the original amount borrowed. The Consumer Financial Protection Bureau (CFPB) says borrowers will want to verify if their loan is a simple interest loan if they plan to pay it off early, as the amount owed gets smaller as the loan is paid down.
Once you learn more about the loan terms, annual percentage rate (APR), and interest rate, you'll get a better picture of the total cost of your vehicle purchase.
This site is for educational purposes only. The third parties listed are not affiliated with Capital One and are solely responsible for their opinions, products and services, and all trademarks listed are the property of their respective owners. Capital One does not provide, endorse or guarantee any third-party product, service, information or recommendation listed above. The information presented in this article is believed to be accurate at the time of publication, but is subject to change. The images shown are for illustration purposes only and may not be an exact representation of the product. The material provided on this site is not intended to provide legal, investment, or financial advice or to indicate the availability or suitability of any Capital One product or service to your unique circumstances. For specific advice about your unique circumstances, you may wish to consult a qualified professional.
Related articles
View more related articles